Finance Your
Production in Spain
Tax Incentives, Financing Structures and International Co-Production Opportunities
Film incentives & financing in Spain can provide international producers with access to tax incentives, financing structures and co-production opportunities for qualifying audiovisual productions. We help international producers assess the appropriate Spanish production structure, incentive territory, financing route and local production framework from the earliest stages of the project.
Two Main Production Paths
International producers generally approach Spain through one of two structures: as an international production shooting in Spain through a local production service company, or as an international co-production with a Spanish producer. The right route affects the applicable incentive, financing opportunities and production structure.
International Service Productions
Foreign feature films, television series and other qualifying audiovisual productions shooting in Spain may access the applicable incentive for international productions through a Spanish production service company, based on eligible expenditure incurred in Spain and the requirements of the relevant fiscal territory.
International Co-Productions with Spain
Selected projects may be structured as international co-productions with a Spanish producer. Where the relevant requirements are met, the Spanish component can potentially access tax incentives, public funding, broadcasters, private investment and other financing sources available to qualifying Spanish productions.
Different Regions. Different Frameworks.
Spain should not be treated as a single uniform fiscal territory for audiovisual production. The general state regime, the Canary Islands, Navarra and the Basque Country operate under different tax frameworks. The appropriate territory depends on the production structure, eligible expenditure, shooting plan and the rules in force when the project is produced.
Mainland Spain
The general state framework for qualifying international productions shooting and incurring eligible production expenditure across most of Spain.
Canary Islands
A distinct economic and fiscal territory with its own audiovisual incentive framework and an established international production ecosystem.
Navarra
A separate foral tax jurisdiction with its own audiovisual incentive framework for qualifying productions and expenditure connected to Navarra.
Basque Country
A territory governed by provincial foral tax systems, with audiovisual incentives determined by the applicable provincial framework.
National Film Incentive Framework
The general Spanish tax framework provides an incentive for qualifying foreign audiovisual productions that incur eligible production expenditure in Spain. For international service productions, the relevant state mechanism is established under Article 36.2 of the Spanish Corporate Income Tax Law.
The available benefit depends on the production, eligible expenditure, applicable thresholds and limits, eligibility requirements and the Spanish production structure through which the project is carried out.
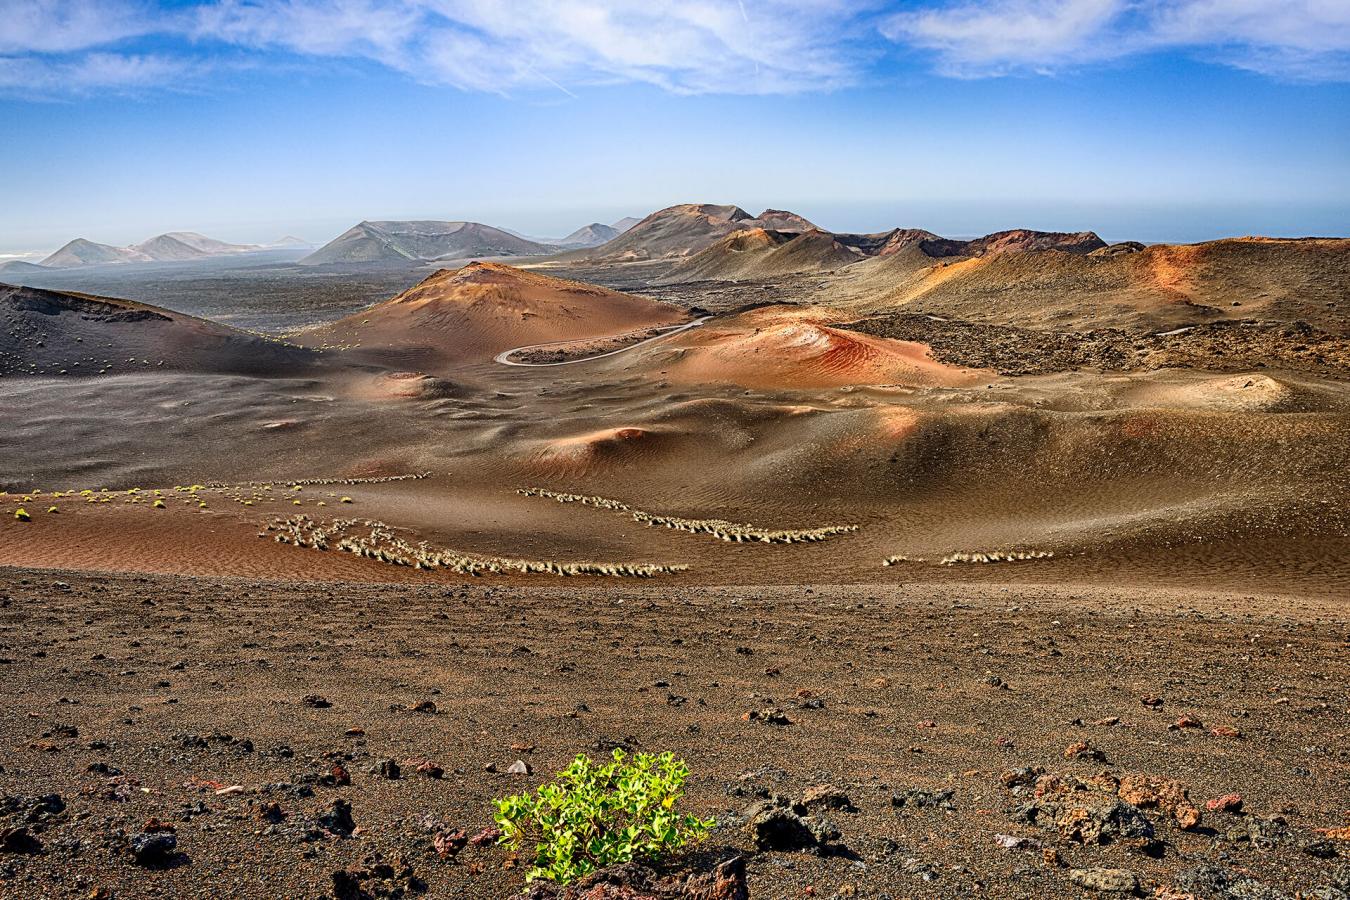
A Distinct Fiscal Territory
The Canary Islands operate under their own Economic and Fiscal Regime and provide a specific audiovisual incentive framework for qualifying international and Spanish productions.
International projects must meet the applicable production, expenditure and local-structure requirements. Combined with experienced crews, production infrastructure and diverse locations, this makes the Canary Islands an important option for productions planning a substantial Spanish production footprint.
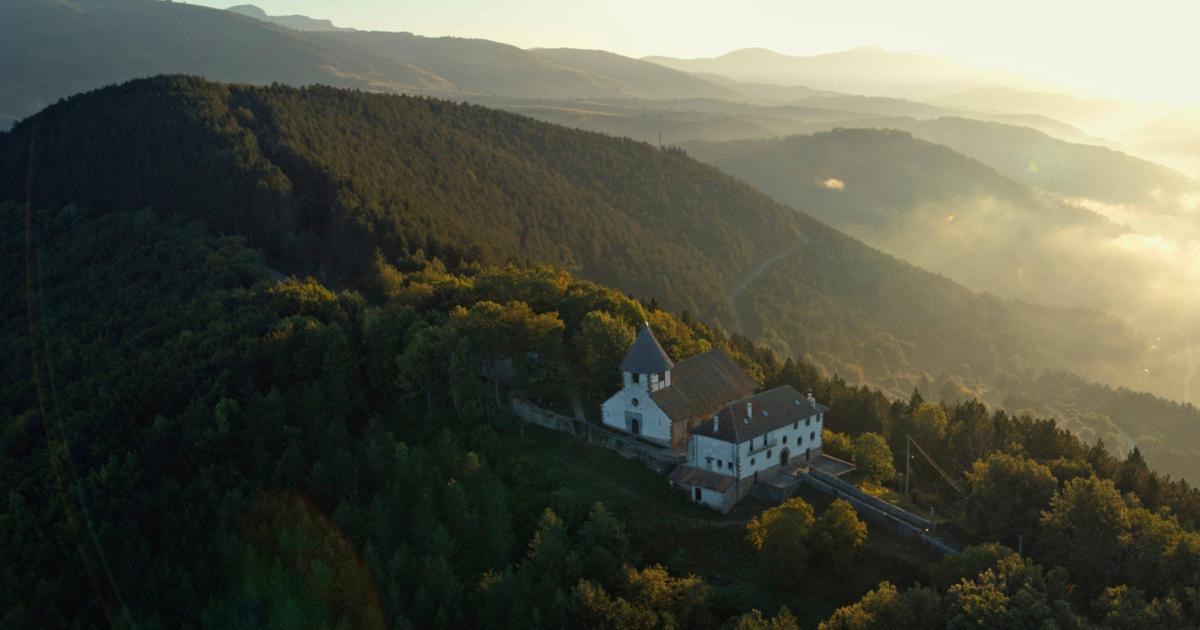
Regional Incentives & Production
Navarra has its own foral tax system and audiovisual incentive framework, separate from the general state regime. It can therefore be evaluated independently when structuring a production in Spain.
Productions considering Navarra should assess the applicable incentive together with eligible expenditure in the territory, production requirements, shooting locations and the wider financing structure of the project.
Provincial Tax
Frameworks
The Basque Country operates through the separate foral tax systems of Álava, Bizkaia and Gipuzkoa. Audiovisual incentive rules can therefore vary according to the province in which the production is structured and eligible expenditure is incurred.
International producers considering the Basque Country should assess the relevant provincial framework alongside the shooting plan, production structure, local expenditure and wider financing strategy.
Beyond the
Tax Incentive
For selected international projects, Spain can contribute more than production services and a tax incentive. Where the project and Spanish participation allow it, the local production or co-production component can form part of a wider financing plan combining private investment, broadcasters and platforms, distribution, international sales, public funding and other project-specific sources.
Tax Incentive Structuring
Identifying the appropriate fiscal territory, production route, eligible expenditure, Spanish production structure and documentation requirements before the local production plan is finalised.
AIE & Tax Investor Structures
For qualifying Spanish productions and co-productions, tax-investor structures, including AIE-based models where appropriate, may form part of the financing strategy, subject to Spanish tax law and the specific structure of the project.
Private Financing
Equity, private investment, gap financing and other project-specific capital can complement the Spanish component of an international financing plan where the project and risk profile support it.
Broadcasters & Platforms
Spanish and international broadcasters, streaming platforms and pay-TV partners may contribute through commissioning, acquisition, pre-buy or licensing arrangements depending on the project.
Distribution & Sales
Spanish distribution, international sales and minimum guarantees can become part of the financing plan for selected feature films and international co-productions.
International Co-Production
International co-productions can combine a Spanish producer and Spanish financing sources with co-producers, incentives, broadcasters, public funds and financing from other territories.
Spain as a Production Partner
For selected international feature films and audiovisual projects, Spain can participate as a producing and financing territory rather than functioning only as a production-service destination.
International co-productions recognised under the applicable Spanish rules and co-production agreements can qualify as Spanish national productions. Subject to eligibility, the Spanish component may therefore access ICAA production support, regional funding, tax incentives and other Spanish financing sources.
The appropriate structure depends on the creative contribution, ownership, financing plan, Spanish participation, production spend and the requirements of each partner territory, so co-production planning should begin early in development.
From Assessment to Implementation
Incentive and financing planning should begin before the Spanish production structure is fixed. We review the project, production budget, expected Spanish spend, shooting territories and financing objectives to determine the most appropriate route and local production structure.
Project Review
Budget, schedule, shooting plan, Spanish expenditure and international financing objectives.
Territory Assessment
Comparing the applicable Spanish fiscal territories, incentives and production implications.
Structure
Defining the Spanish production-service, co-production, incentive and financing structure.
Production
Managing local production, eligible expenditure, accounting controls and supporting documentation.
Close-Out
Final accounting, documentation, certification coordination and implementation of the agreed structure.
Key Questions for International Producers
Bringing an International Production to Spain?
Talk to us before your Spanish production structure is locked. We can review your preliminary budget, shooting plan, expected Spanish expenditure and financing objectives to assess the relevant incentive territory, production-service or co-production route and the local production structure required to deliver the project in Spain.